If you inherited a house in Oregon with a mortgage, the loan doesn’t disappear when the owner dies. Heirs generally are not personally liable for the debt unless they signed or assumed the obligation, and federal law usually prevents a lender from calling the loan due solely because an eligible relative inherited the home. After getting legal advice, you may be able to keep the property and continue payments, refinance, sell it and pay off the mortgage at closing, or decline the property.
I am Quinn Irvine, owner of Portland Cash Buyers, and I have bought Portland-area homes since 2004. This guide covers a traditional mortgage or trust deed loan. A reverse mortgage works on a different clock, so the rules below do not fit that loan type.
Here are five things many heirs do not hear at the start:
- Oregon counts the full value of the house, without subtracting the mortgage, when it decides whether an estate can use the simple estate affidavit.
- A loan servicer must have a process to confirm who you are, and you can ask about assuming the loan before anyone pushes a refinance.
- A surviving spouse or dependent child who lives in the home may stay up to one year, but must keep up the insurance and taxes.
- Property taxes and insurance keep coming due while the estate is open, and a missed installment can cause its own trouble.
- When a sale generates enough proceeds to cover the mortgage and other required closing obligations, the title company can pay the lender from the proceeds. If the property is underwater, the lender may need to approve a short sale or another payoff arrangement before the transaction can close.
What Happens to a Mortgage When the Homeowner Dies?
The loan stays in place after the homeowner dies, and it stays with the house. Nothing in the loan changes on the day of the death. The balance, the interest rate, and the payment schedule all continue. The servicer keeps sending statements to the borrower’s address, and the payments are still due. Someone has to decide how they will be made. That is usually the person named in the will as personal representative, or a family member working with the court.
The loan stays with the property, not the heirs
A mortgage or trust deed creates a lien on the property as security for repayment of the debt. In Oregon, lenders commonly use trust deeds to secure home loans. When the property owner dies, title may pass to the heirs or devisees subject to existing liens and creditors’ rights. According to the Oregon State Bar, a trust deed gives the lender rights against the property until the secured debt is repaid. Thus, inheriting the property does not eliminate the lender’s security interest, although the heirs do not automatically become personally liable for the deceased owner’s mortgage debt merely by inheriting the property
Oregon adds a rule of its own. Under ORS 115.255, when a house subject to a mortgage is specifically devised under a will, the beneficiary generally inherits it subject to the mortgage, and the estate is not required to pay off the debt. However, under ORS 115.255(3), certain exceptions allow the mortgage to be paid from other estate assets. In plain words, you may inherit a house with its mortgage still attached rather than having the estate automatically pay off the loan. The wording of the will and the circumstances of the estate matter, so consult a probate attorney for guidance
Are heirs personally responsible for the debt?
No, not unless you signed the loan or assumed it. The federal servicing rules say this directly. They include a sample notice telling a successor in interest that they are liable for the mortgage debt only if they assume the loan under state law. You can read the rules in the CFPB’s mortgage servicing regulation. The house still secures the debt, though. If payments stop, the lender can look to the house. That is why the loan has to be handled before or at a sale. An Oregon probate attorney can tell you how this works for your estate.
Federal Protections for Heirs: Garn-St Germain and “Successor in Interest” Rules
Two federal protections help heirs: the Garn-St Germain Act limits due-on-sale demands, and the CFPB’s successor-in-interest rules give heirs a way to deal with the servicer. Together they answer the two fears I hear most. Can the bank take the house right away? Will anyone even talk to me about the loan? Neither law turns the loan into a gift. They give you time and a seat at the table.
Why the lender usually can’t call the loan due
Most mortgages include a due-on-sale clause, and federal law blocks the lender from using it on a transfer to a relative after the borrower dies. Under 12 U.S.C. 1701j-3, a lender may not exercise that clause on a transfer to a relative that results from a borrower’s death. The same section also covers a transfer where the borrower’s spouse or children become owners. The rule applies to loans on residential property with fewer than five dwelling units.
There are limits. A friend or an unmarried partner may not have the same protection. A transfer outside these categories may not be covered. If you are not sure where you fit, ask an Oregon attorney before you rely on this rule.
How to become a confirmed successor in interest and get loan information
Send your servicer proof of the death and proof of your ownership interest, and the servicer must work through the federal process to confirm your status. A confirmed successor in interest counts as a borrower for most servicing rules. That is true even if you have not assumed the loan. The servicer must have policies to identify heirs and tell them which documents it needs. These items usually help:
- A certified copy of the death certificate.
- A copy of the will, or a letter from the personal representative.
- Your photo identification.
- The loan number and the property address.
- A short written request for the payoff amount and the loan terms.
The CFPB explains how to get mortgage information about a home you inherited. Once you are confirmed, you can also ask about payment help and request a payoff statement.
Some servicers steer heirs toward a refinance. The CFPB has reported homeowner complaints about problems after a death or divorce, including that kind of pressure. Ask whether assuming the existing loan is possible before you agree to anything.
Who Makes the Mortgage Payments During Oregon Probate?
The personal representative decides how to keep the loan current, usually from estate funds, once the court issues letters. Until then, a family member often advances the payments to keep the loan from falling behind. Keep every receipt. A probate attorney can tell you how to be repaid from the estate.
The personal representative’s role and using estate funds
The personal representative’s powers begin when the court issues letters, and the role comes with a duty to settle the estate with as little loss of value as is reasonable. Being named in a will is not enough. The Oregon Judicial Department says you are not the personal representative until the court appoints you. Probate cases are filed in the circuit court for the county where the person lived. In the Portland area, that usually means the Multnomah, Washington, or Clackamas County court. For the basics, read my post on how Oregon probate works.
Estate funds often cover the mortgage, taxes, and insurance while the estate is open. Oregon property tax installments are due November 15, February 15, and May 15, so check your county tax statement for dates and amounts. If the estate is small, a simple estate affidavit may replace full probate. Under ORS 114.510, it applies only when no more than $75,000 of the estate is personal property and no more than $200,000 is real property. The value counts without subtracting liens or debts. Here is an example, not a real case. A $350,000 house with a $250,000 mortgage counts as $350,000 of real property, so it would not qualify. Oregon has changed these limits in recent years, so confirm the current numbers with the court or an attorney.
A surviving spouse or dependent child who lives in the home has a separate protection. ORS 114.005 lets them stay up to one year after death. During that year, they must pay insurance and taxes, and the lender’s security interest stays in place.
What happens if payments are missed
The lender can start foreclosure after a default, but federal and Oregon rules slow the process and point you to free help. My post on the Oregon foreclosure timeline walks through the steps. Under the CFPB’s guidance, a servicer generally cannot make the first notice or filing for foreclosure until you are more than 120 days behind. In Oregon, a nonjudicial foreclosure begins with a recorded notice of default and election to sell. The notice of sale goes out at least 120 days before the trustee sale, as laid out in ORS chapter 86. The state’s own page on the Oregon foreclosure process also describes the Oregon Foreclosure Avoidance program.
The CFPB also lists HUD-approved housing counselors, and foreclosure prevention counseling from these agencies is free. I cannot tell you what your lender will do in your case. A foreclosure attorney or a housing counselor can. If the estate is already behind, my page on being behind on mortgage payments covers that side.
Your 4 Options for an Inherited House With a Mortgage
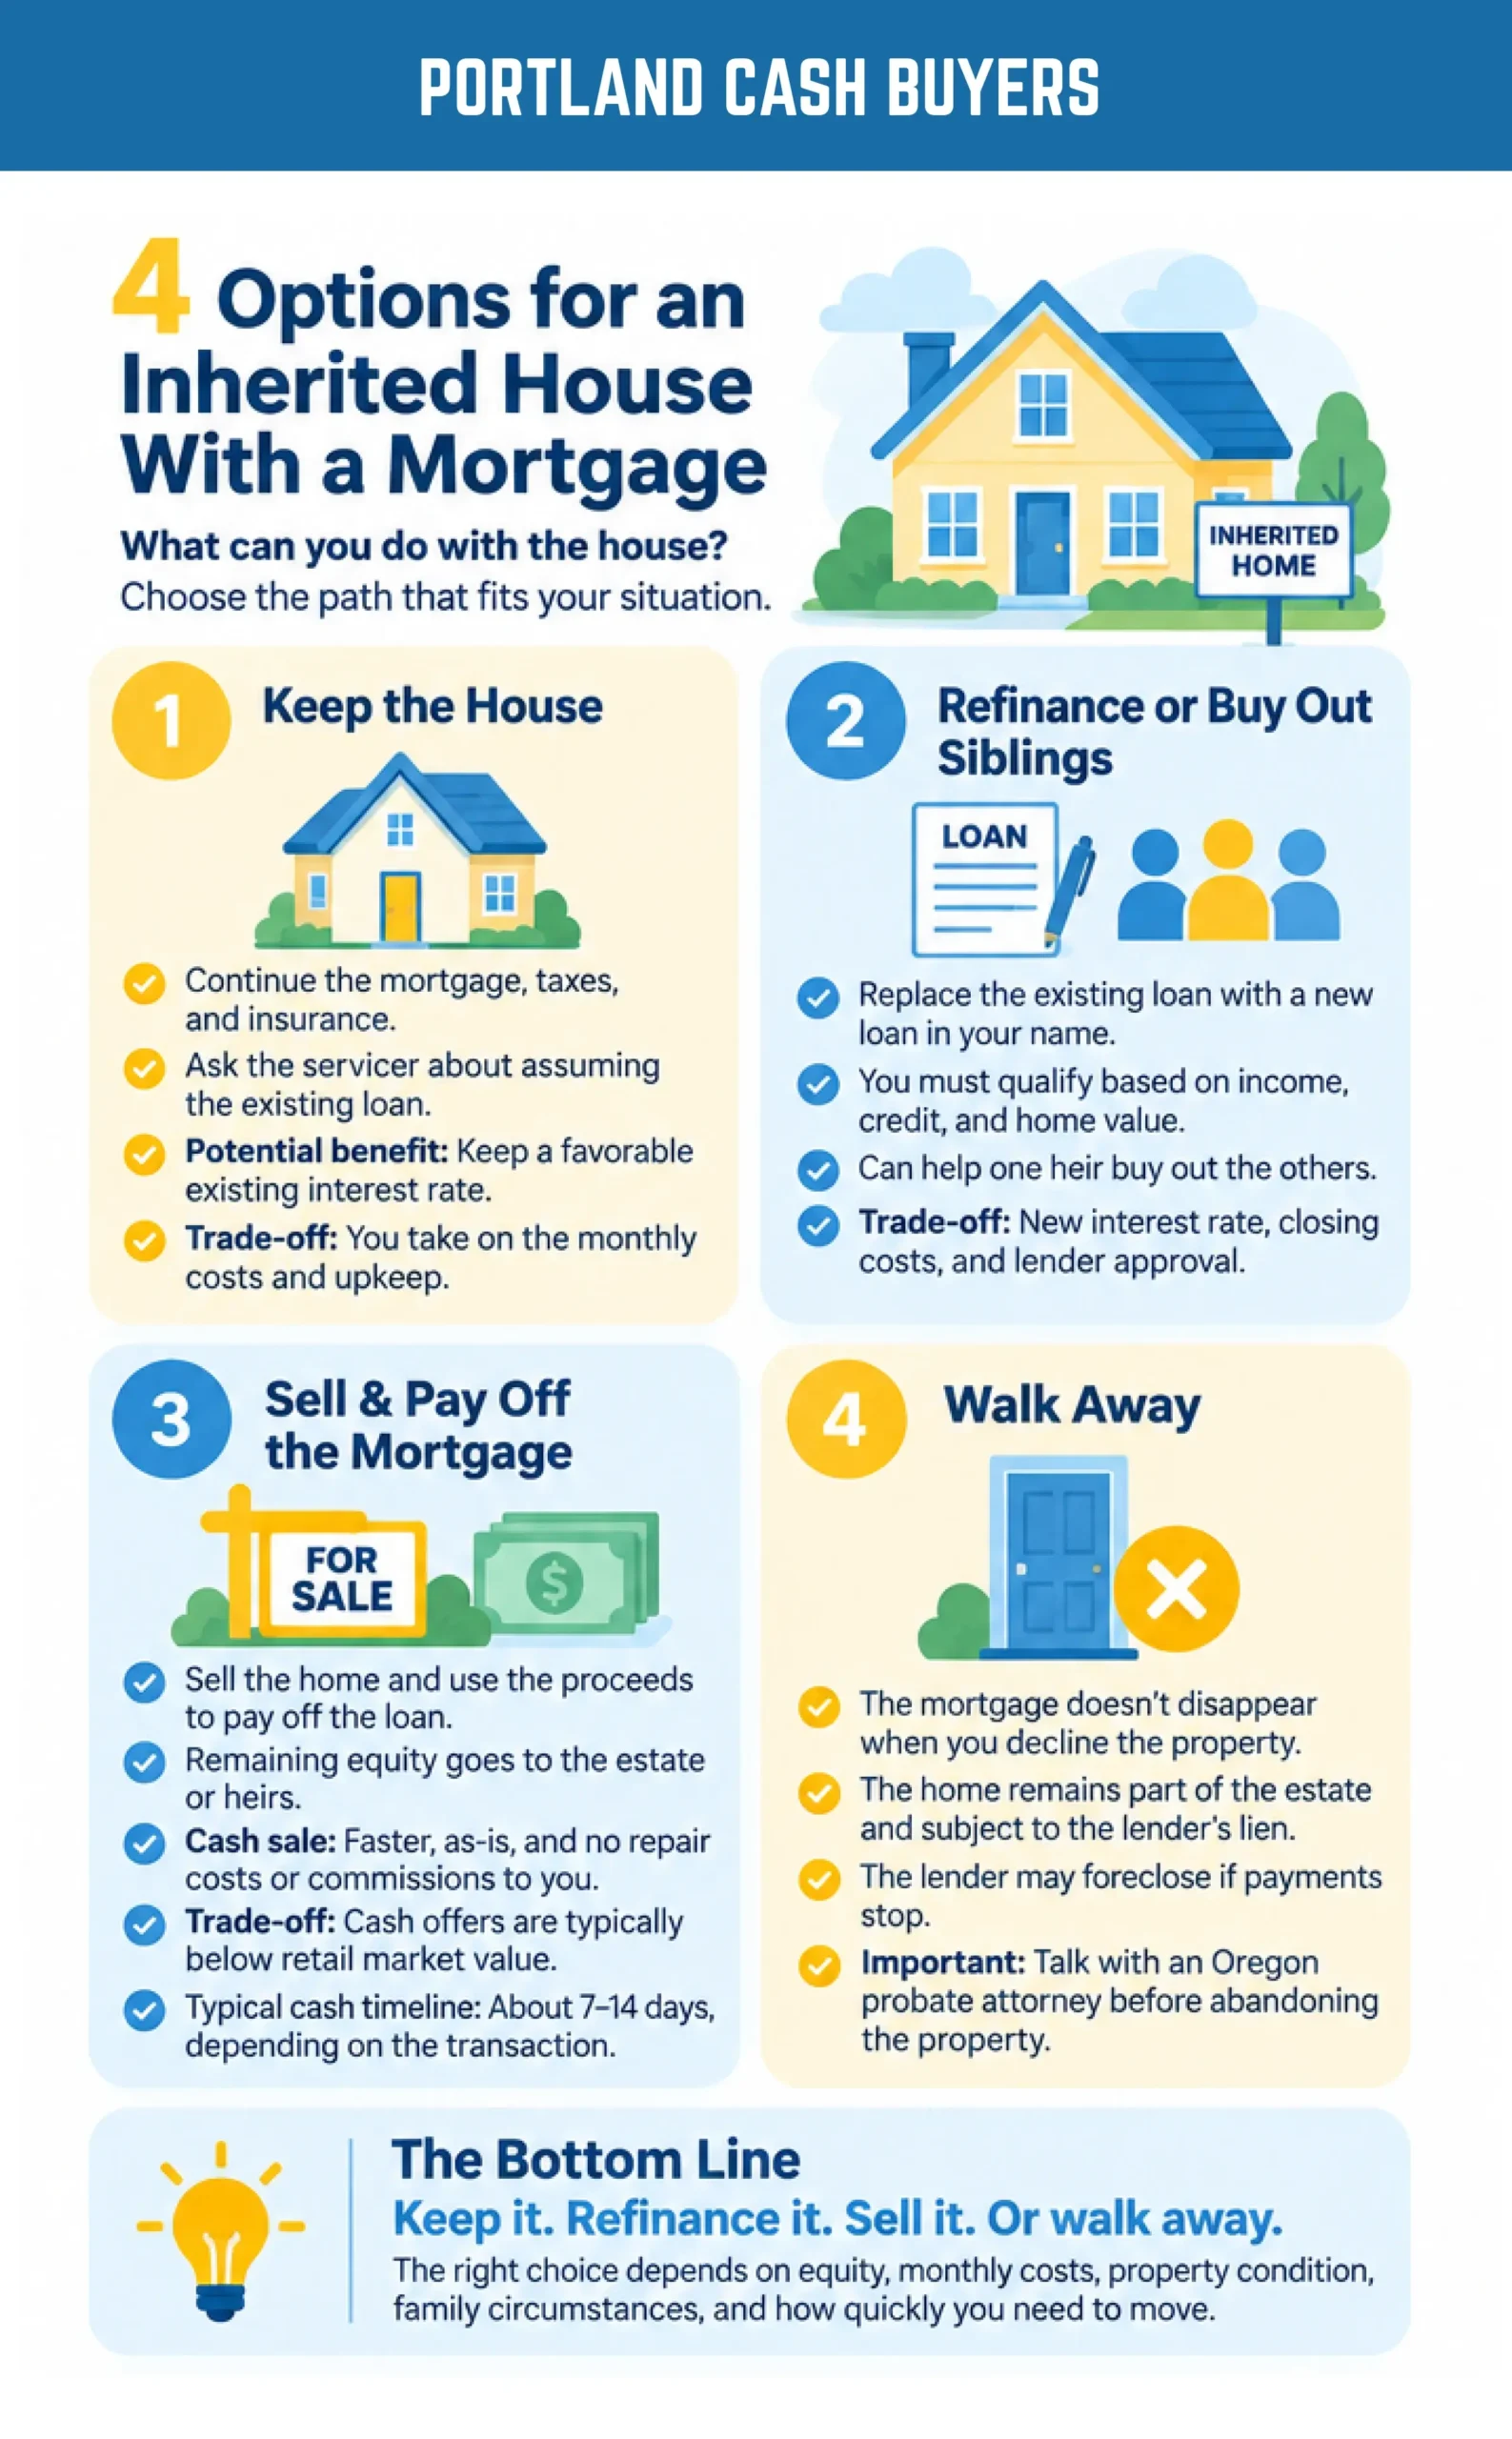
You can keep the house and take over the payments, refinance into your own name, sell and pay off the loan at closing, or walk away. Each path fits a different situation. The table shows the trade-offs side by side.
| Option | Fits best when | Main trade-off | Speed |
| Keep and take over payments | You can carry the loan, taxes, and insurance | You take on a monthly bill and the upkeep | You decide the pace |
| Refinance into your name | You qualify and want a new loan or a sibling buyout | New rate, new costs, and lender approval | Weeks |
| Sell and pay off at closing | You want out, or the house needs work | Price may be lower than a listing | 7 to 14 days with cash |
| Walk away | The house has no equity and no use to the estate | The lender can foreclose, so talk to an attorney first | Depends on the lender |
Option 1: Keep the house and take over payments
You may be able to keep the home and continue making the scheduled payments without automatically becoming personally liable for the loan. A formal assumption is a separate step, so ask the servicer to confirm you as a successor in interest and explain whether you can assume the existing loan. If assumption is available, compare the current rate and terms with a refinance. Also account for insurance, property taxes, repairs, and any overdue amounts before deciding whether keeping the house is affordable.
Option 2: Refinance into your own name (or to buy out siblings)
Refinancing replaces the old loan with a new one in your name, and you must qualify for it. That means the lender looks at your income, credit, and the value of the house. A refinance can also let one heir buy out the others. If you share the house with brothers or sisters, my guide to inherited a house with siblings explains how shared ownership works. Compare the new rate and closing costs with simply assuming the old loan.
Option 3: Sell the house and pay off the loan at closing
Selling can allow the mortgage to be paid from the closing proceeds, with any remaining funds distributed to the estate or the people legally entitled to receive them. Before choosing a sale, compare a traditional listing with an as-is cash offer, including the estimated sale price, mortgage payoff, other liens, closing costs, repairs, and carrying costs. If you prefer a faster sale without preparing the property for showings, you can sell an inherited house in Portland without completing repairs first, subject to the seller’s legal authority and the transaction terms.
My cash offer will be lower than retail, but the gap that matters is what you net. After commissions, repairs, seller closing costs, and months of carrying costs, the difference is often smaller than the sticker price suggests. The table below is an example scenario with round numbers. It is not a quote or a promise for your home.
| Line item (example only) | List the house | Cash sale to me |
| Price | $400,000 listing price | $360,000 cash offer (placeholder) |
| Commissions at 5.22% | -$20,880 | $0 |
| Seller closing costs (assumed) | -$4,000 | $0, I pay all closing costs |
| Repairs and cleanout (assumed) | -$5,000 | $0, I buy as-is |
| Carrying costs (assumed $2,500 a month) | -$7,500 (3 months) | -$1,250 (about 2 weeks) |
| Net before mortgage payoff | $362,620 | $358,750 |
| Typical timeline | Showings, inspection, buyer financing, and appraisal add weeks or months | 7 to 14 days to close; as little as 7; fastest I have closed is 3 |
The commission rate comes from Clever Real Estate’s August 2026 survey of real estate professionals, which reports 5.22 percent for Oregon. The National Association of Realtors notes that commissions are fully negotiable. I assumed the other dollar figures to show the arithmetic. The mortgage payoff comes out of both columns equally, so I left it off.
In this example, listing nets about $3,870 more. That holds only if the house sells at asking price and on schedule. A $5,000 price cut erases the gap. So do one more month of carrying costs and a $1,500 repair bill. If your house is in good condition, you have a few months, and the market is strong, list it. A cash sale is the right tool for speed and simplicity, not for topping the market. I am not quoting a percentage here. My real offer depends on recent comparable sales, the home’s condition, repair costs, and carrying costs, and I walk you through each one.
Before accepting a cash offer, confirm the closing costs, what happens to personal belongings, whether a leaseback is available, and the agreed move-out date in writing. If multiple heirs are involved, make sure the personal representative has authority and that all required parties agree to the transaction. An as-is sale may save time and repair costs, but compare the expected net proceeds with a traditional listing before deciding.
Before you pick any buyer, ask whether they take the title in their own name or plan to assign the contract. A wholesaler holds only an equitable interest and sells the contract to someone else. House Bill 4058 (Chapter 3, Oregon Laws 2024) began requiring residential property wholesalers to register with the Oregon Real Estate Agency on July 1, 2025. The agency’s overview of property wholesaling explains the law, and an Oregon real estate attorney can answer questions about your own deal. I take titles in my own name, and I do not assign contracts. I provide proof of funds on request, as a bank letter or statement. Those are my practices, not a legal opinion. A cash sale has no financing contingency, so the deal cannot fall through because a buyer’s lender declined.
That is one option, not the only one. If you would like to talk through all four, call or text me at (503) 770-0145. I answer seven days a week, from 8 am to 8 pm, and a call carries no obligation.
Option 4: Walk away (and what that means for the estate)
You can decide not to keep the property, but the mortgage lien does not disappear. Under Oregon law, title generally passes to heirs or devisees at death, subject to creditor rights, estate administration, and the personal representative’s authority to sell the property. If payments stop, the lender may foreclose. Under ORS 114.305, a personal representative may abandon property that is valueless or so encumbered that it offers no benefit to the estate. Consult an Oregon probate attorney before taking that step. If the property has equity, an authorized sale may preserve the remaining value for the estate or its beneficiaries.
What If the Inherited House Is Underwater?
An underwater house is worth less than the loan, and you are generally not personally liable for the shortfall unless you signed or assumed the loan. That does not make it simple. The lender still holds a lien, and the sale price has to cover the payoff or the lender has to agree to take less. A cash sale only works when one of those two things is true. The lender makes that call, not me.
Short sale basics
A short sale is a sale for less than the loan balance, and the lender must approve it. The estate or the heirs ask the servicer for approval, and the lender usually wants to see the offer, the hardship, and the value of the house. Approval takes time. Ask an attorney how a short sale affects the estate before you sign. Ask the title company to confirm in writing what the lender agreed to accept.
Second mortgages, HELOCs, and other liens
Every loan or lien on the house gets paid from the sale proceeds, and the title commitment shows all of them. A second mortgage or a home equity line of credit (HELOC) is a separate loan with its own servicer. Property tax liens, contractor liens, and court judgments can also attach to the house. Lawyers Title of Oregon describes how escrow orders payoff demands and clears liens before a sale closes. Ask the servicer of each loan for a payoff statement. Then add them up before you set a price.
Step-by-Step: Selling an Inherited House That Still Has a Mortgage
Selling usually involves three steps: request a written mortgage payoff statement, confirm who has legal authority to sign for the property, and let the title company coordinate the closing. If the sale proceeds cover the mortgage and other liens, the title company can pay them from the proceeds and distribute the remainder to the estate or the eligible owners. If the proceeds are insufficient, the lender may need to approve a short sale or another payoff arrangement. Do not assume the transaction can close until the payoff requirements are confirmed.
Request a payoff statement
Ask the servicer for a written payoff statement that shows the balance through your expected closing date. A confirmed successor in interest or the personal representative can request it. The statement shows the principal, interest, and any fees. Ask for a new one if the closing date moves.
Confirm authority to sell
You need legal authority to sign, usually court-issued letters or a filed simple estate affidavit. The title company will ask to see it. Once appointed, a personal representative can usually sell estate property without a court order or notice, though some estates have court-ordered limits. Liens survive the sale, which is why the mortgage is paid at closing. If several heirs own the house, they all need to be part of the decision.
How the title company distributes proceeds
The licensed title company pays the lender first and sends what is left to the estate or the heirs. Closing happens at a licensed and insured title company in Portland. You can reach the title company, as well as me, for status updates. The steps look like this:
- The title company runs a title commitment that lists the mortgage and any other liens.
- The servicer’s payoff statement sets the amount owed through the closing date.
- At closing, the title company sends the lien payoff to the servicer from the sale proceeds.
- The lender records a release, and the title company sends the remaining money to you or the estate.
My offer does not change at closing, with no last-minute deductions and no hidden fees. Timing depends on your paperwork. Once you have authority to sell, a typical close takes 7 to 14 days. It can take as little as 7, and the fastest I have closed is 3 days. A title defect, a probate delay, or a lien surprise can slow any closing, mine included. I would rather say that now than later.
Taxes come next. The IRS says the basis of inherited property is generally its fair market value on the date of death, and it explains this in Gifts and inheritances. That can affect any gain when you sell. My post on capital gains on an inherited house goes deeper. Oregon requires an estate return when total estate assets were $1 million or more at death, and the estate pays that tax, not the heirs, per the Oregon Department of Revenue. I do not give tax advice. Talk with a tax professional.
Frequently Asked Questions about Inheriting a House With a Mortgage in Oregon
Can the bank take an inherited house?
Not just because the owner died. If the house passes to a relative, federal law usually blocks the lender from demanding the full balance for that reason. If payments stop, though, the lender can start foreclosure under Oregon’s trust deed process. Keep the loan current and contact the servicer early. Ask an Oregon attorney about your case.
Do I have to notify the lender of a death?
Yes, tell the servicer soon. The servicer cannot discuss the account with you until you show proof of your right to the home. Send a death certificate and a will or a letter from the personal representative. Keep a copy of everything you send and a note of each call.
Can I get a loan modification on an inherited mortgage?
Possibly. Federal rules let a confirmed successor in interest ask about payment help the way the original borrower could. Whether you qualify depends on the loan and the servicer’s programs. A HUD-approved housing counselor can help you apply, and the help is free. Do not pay anyone upfront for a modification.
What if there is no money in the estate to pay the mortgage?
Talk to a probate attorney and the servicer right away, and look at selling the house. Heirs generally are not personally liable for the loan, but the lender can still foreclose on the house. If the house has equity, a sale can pay the loan and leave money for the estate. If it does not, the lender may agree to a short sale. A housing counselor can walk you through the options.
Can I sell an inherited house with a mortgage before probate is finished?
You do not need probate finished, but you need legal authority to sign. That usually means court-issued letters or a filed simple estate affidavit. The title company will ask to see it. An Oregon probate attorney can tell you which one fits. Then I can work from the closing date you choose.
Is selling for cash always the right move for an heir with a mortgage?
No. A cash sale is right for speed and simplicity. If the house is in good shape and you have time, listing may net more, and keeping it may suit you better. I will tell you plainly which way the numbers point for your house.
Your Next Steps for an Inherited House With a Mortgage in Oregon
An inherited house with a mortgage in Oregon gives you real choices, and none of them has to be settled this week. Keep the loan current, ask the servicer to confirm you as a successor in interest, and learn your options before you sign anything. If you sell, the mortgage is paid from the proceeds at closing. To see numbers, get your cash offer, and I will personally give you a fair, no-obligation cash offer within 24 hours. Or call or text me at (503) 770-0145, seven days a week, from 8 am to 8 pm. If listing is the better move, I will say so.
This article is general information, not legal or tax advice. Talk with an Oregon probate attorney and a tax professional about your own estate.