If you inherited a house with a reverse mortgage, selling an inherited house for cash in Portland may be one option, but understanding the servicer’s deadline comes first. I’m Quinn Irvine, owner of Portland Cash Buyers, and I have bought Portland-area homes since 2004. This guide focuses on FHA-insured Home Equity Conversion Mortgages (HECMs), which follow federal rules that may differ from those of private reverse mortgages.
For a HECM, the loan generally becomes due after the last surviving borrower dies, unless a surviving co-borrower or eligible non-borrowing spouse has protection. The estate and heirs generally are protected from personal liability for a qualifying loan shortfall, but the property itself remains collateral. The due-and-payable notice sets out the immediate deadlines. Additional time to sell or pay off the loan may be available, including extensions subject to approval.
A few points most heirs only learn late in the process:
- The clock that matters is usually the servicer’s, not probate’s. The due and payable notice can move faster than an Oregon probate case.
- An underwater house costs the heirs nothing extra. A sale for at least 95% of the appraised value satisfies the loan, even when the balance is higher.
- That 95% floor cuts both ways. A discounted cash offer may fall below it on an underwater house, so a quick sale is not always the right tool.
- Extensions are earned with paperwork. Keep a written record of every listing agreement, purchase agreement, and payoff request you send.
What Happens to a Reverse Mortgage When the Borrower Dies?
When the last borrower dies, the reverse mortgage becomes due and payable, and the loan must be repaid, usually by selling the home. The Consumer Financial Protection Bureau’s guide to reverse mortgages after death explains that the outcome depends on three things. Was there a co-borrower? Does a spouse qualify for protection? When was the loan made?
A reverse mortgage works backward from a regular loan. Your parent made no monthly payments. Interest and mortgage insurance were added to the balance instead. So the balance grew every month while the home stayed in their name. At death, the whole balance comes due at once.
The servicer usually learns of the death from a family member, a returned check, or public records. Then it sends a due and payable notice. Do not set that letter aside. Here is what I would do in the first two weeks:
- Find the most recent loan statement. It lists the servicer’s name, phone number, and the current balance.
- Call the servicer, report the death, and ask for a payoff statement and the deadlines in writing.
- Tell the servicer in writing what you plan to do: sell, pay off, or hand back the house.
- Keep the property taxes and homeowners insurance current, and secure the empty house.
- Call a HUD-approved housing counselor. HUD’s heir guide lists how to reach one at no cost.
One caution. Everything in this guide describes the federal HECM program. A private, or proprietary, reverse mortgage follows its own loan documents. If yours is not a HECM, read the note and deed of trust, or ask an Oregon attorney to read them with you.
How Long Do Heirs Have? The Reverse Mortgage Timeline
The due-and-payable notice is the first document to check because it identifies the immediate deadline and your options. Current CFPB guidance says heirs generally have 30 days after receiving the notice to buy, sell, or turn over the home to satisfy the debt. Additional time to sell or pay off may be available, including up to two further 90-day extensions when HUD approves the request and the heirs provide evidence that they are actively marketing the property. Do not assume an extension is automatic. Ask the servicer to confirm your exact deadline in writing and submit any extension request before the current period expires.
| Stage | Typical HECM timing | What the heirs do |
| Borrower dies | Day zero | Find the loan statement and notify the servicer |
| Due and payable notice | Sent after the servicer learns of the death | Read it closely and note every date |
| Response window | About 30 days from the notice | State your plan in writing |
| Sell or pay off window | Up to 6 months from the due date | List, sell, refinance, or arrange a deed in lieu |
| Extensions | Up to two 90-day extensions, if approved | Send proof you are actively selling or repaying |
| Foreclosure | After the windows and any extensions end | Avoid reaching this stage if you can |
The Six-Month Window to Sell or Pay Off a Reverse Mortgage
Six months sounds like plenty. In practice, it goes fast. You may need to open probate, clear out a lifetime of belongings, and agree with siblings on a price. Each step eats weeks.
HUD’s guide says the servicer may approve 90-day extensions when there is satisfactory proof that the heirs are actively trying to sell or repay. That means documents, not phone calls. A signed listing agreement, a purchase agreement, or a loan application all show progress. Ask the servicer exactly what it needs, and send it before the current window closes.
If the windows end with no sale, payoff, or deed in lieu, the servicer can begin foreclosure. That is a separate process with its own rules. My page on facing foreclosure explains how it generally works in Oregon.
If you are partway through this timeline and want a firm number to plan around, call or text me at (503) 770-0145. I answer seven days a week, 8 am to 8 pm. I give a cash offer within 24 hours of your request, and you choose the closing date.
Do Heirs Owe More Than the House Is Worth?
A qualifying HECM is a non-recourse loan, which generally protects the estate and heirs from personal liability for the eligible shortfall after the property is resolved under the applicable loan rules. If the balance is higher than the home’s value, heirs may be able to sell for at least 95% of the current appraised value, allowing the lender to accept eligible sale proceeds as payment in full. The servicer must confirm the applicable payoff and sale requirements. Private reverse mortgages may follow different terms, so check the original loan documents.
This protection matters most for long-held reverse mortgages. Interest compounds for years. A loan taken out at 70 can outgrow the house by 90, especially if values dipped along the way. Even then, the heirs do not write a check for the difference. The loan was built for that outcome.
The 95% Rule for an Underwater HECM Home
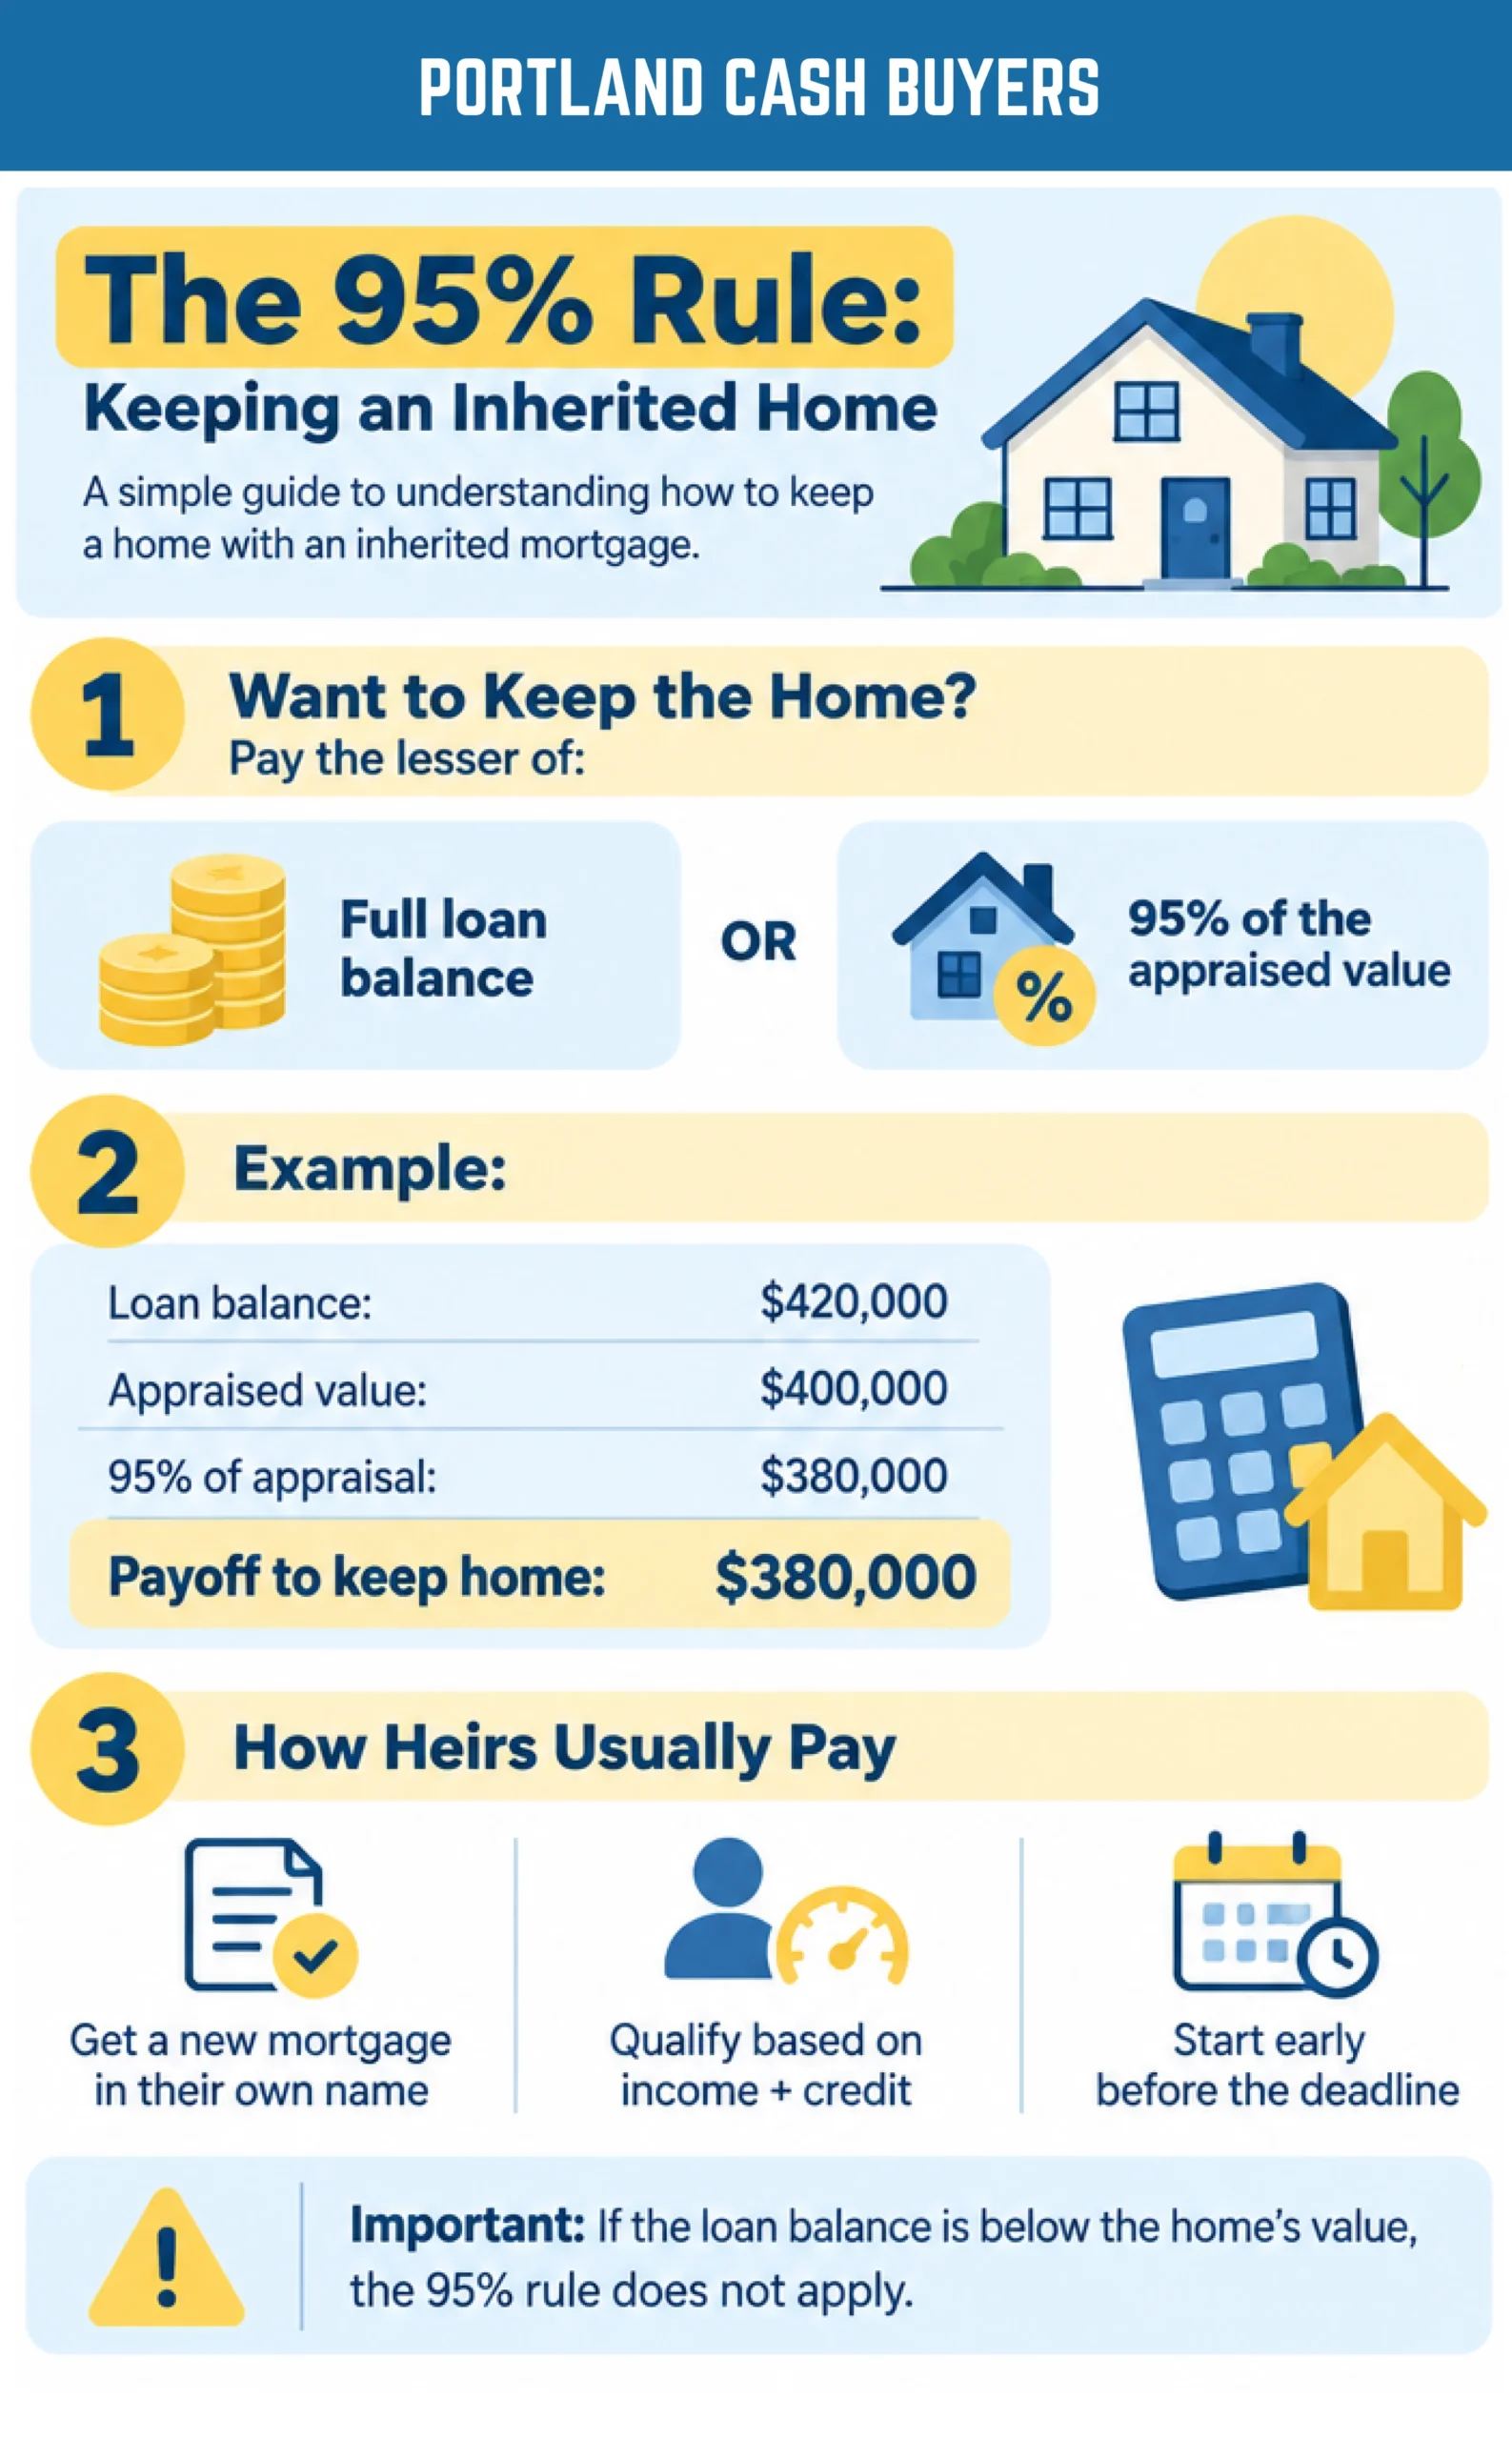
When a HECM balance exceeds the home’s appraised value, federal guidance generally allows the estate or heirs to sell the property for at least 95% of its current appraised value, subject to the applicable HECM rules. If the home appraises at $400,000, 95% equals $380,000. If the sale price meets the applicable threshold, the lender may accept the eligible net sale proceeds as payment in full, with FHA mortgage insurance covering the remaining eligible shortfall. Confirm the payoff requirements with the servicer before accepting an offer.
Most heirs pay that amount with a new mortgage in their own name. That means qualifying with a lender on your own income and credit, within the same deadline. Start the loan application early. If the balance is well below the home’s value, the 95% rule does not apply, and you pay the full balance.
Your Options as an Heir
An heir has four realistic choices: sell and keep the equity, pay off the loan to keep the house, hand the house back through a deed in lieu of foreclosure, or do nothing and let foreclosure happen. Each fits a different situation.
| Option | Fits when | Watch for |
| Sell and keep the equity | The house is worth more than the loan balance | Interest keeps adding to the balance until closing |
| Pay off or refinance to keep it | An heir wants to live in it and can qualify for a loan | The loan must close inside the servicer’s window |
| Deed in lieu of foreclosure | The house is underwater, and nobody wants it | Ask the servicer how the handover and any incentive work |
| Do nothing | Never the right plan | Foreclosure, lost equity, and months of empty-house costs |
Sell the Inherited House and Keep the Remaining Equity
Selling is the most common path when there is equity. The mechanics are the same as any home with a loan on it. The title company orders a payoff statement from the reverse mortgage servicer. At closing, it pays the servicer from the sale proceeds. The estate receives what remains.
You can sell two ways. A listing with a broker usually brings the highest price, but it takes showings, repairs, and a buyer whose loan must close. A sale to a local cash buyer trades some price for speed and certainty. When I buy, there is no financing contingency, so the deal cannot fall through because a buyer’s lender said no. I buy as-is, and you can leave belongings behind.
A deed in lieu means the estate signs the house over to the lender instead of going through foreclosure. It makes sense when the house is underwater, and no heir wants it. Ask the servicer whether any relocation or cooperation incentive applies to your loan.
Doing nothing is the one choice I would steer anyone away from. The house sits empty, insurance can lapse, and the servicer can foreclose. If the timeline has already run long, my guide on how to sell before a foreclosure auction covers the late-stage options.
Surviving Spouses and Non-Borrowing Spouses
A surviving spouse who was a co-borrower can stay in the home and keep receiving loan payments, as long as the loan’s obligations are met. That comes straight from the CFPB. Nothing comes due at the first death in that case.
A spouse who was not on the loan is different. For HECMs with case numbers assigned on or after August 4, 2014, an Eligible Non-Borrowing Spouse may be able to stay in the home. That spouse receives no more money from the loan, though. Certain conditions apply, such as being married to the borrower when the loan was made. Older loans follow older, narrower rules. A surviving spouse should call the servicer right away and ask which rules cover the loan.
For a spouse who stays, the reverse mortgage is only one piece. Property taxes, insurance, and upkeep still have to be paid. If the house no longer fits your budget or your health, my page on selling a home in retirement walks through what a sale on your own schedule looks like.
How Oregon Probate Affects a Reverse Mortgage Sale
Oregon probate controls who can sign the sale, not whether the reverse mortgage deadline applies. If the house was in your parent’s name alone, start probate early. The servicer’s clock does not pause for the court.
In a typical Oregon probate, the circuit court in the county where your parent lived appoints a personal representative. The court issues letters that prove that person’s authority. The title company needs those letters before it can close a sale. Oregon’s rules for opening an estate are in ORS Chapter 113. If the house was in a living trust, the successor trustee usually signs instead, and probate may not be needed.
Getting Authority to Sell Before the HECM Deadline
Probate timing varies by county and by how complicated the estate is. That is why I tell heirs to file early and keep the servicer informed. Send the servicer a copy of the probate filing and the letters once they issue. Send any listing or purchase agreement too. Those documents are the same proof you will need to request an extension.
Siblings add another layer. Everyone may agree to sell but disagree on price or timing. My guide on selling an inherited house with multiple heirs covers how families usually work that out. For your own estate’s deadlines and authority, confirm the details with an Oregon probate attorney.
Example: Equity vs. Underwater Reverse Mortgage Homes
A home with equity may leave money for the estate after the reverse mortgage and selling costs are paid. An underwater HECM may still qualify for a sale under the 95% rule, but the servicer must confirm the applicable requirements. The table below uses round numbers for illustration only. In Home B, the property appraises at $400,000, making 95% equal to $380,000. The example sale price is $390,000 before the assumed selling costs. Those costs reduce the money available at closing, so confirm the payoff arrangement and treatment of expenses with the servicer before relying on the figures.
| Line item (example scenario) | Home A: equity | Home B: underwater |
| Appraised value | $500,000 | $400,000 |
| Reverse mortgage balance | $300,000 | $460,000 |
| HUD minimum sale price (95% of appraisal) | Does not apply | $380,000 |
| Example sale price | $480,000 | $390,000 |
| Closing and selling costs (assumed for this example only) | $15,000 | Paid from proceeds |
| Paid to the servicer | $300,000 | Net proceeds, accepted as payment in full |
| Left for the estate | $165,000 | $0 |
| Owed by heirs after closing | $0 | $0 |
Home A is where time costs real money. Interest keeps adding to the $300,000 balance every month the house sits unsold. A faster sale protects more of the $165,000. Taxes may also apply to a sale. Heirs often receive a stepped-up basis, which IRS Publication 551 on the basis of assets explains. My post on stepped-up basis and capital gains covers the Oregon side. Talk to a tax professional before you close.
Home B is different. The heirs receive nothing either way. Their real goals are to avoid foreclosure, avoid carrying costs, and move on. A listing that clears the 95% floor works. A deed in lieu also works. A discounted sale that falls below $380,000 would need the servicer’s approval, and you should not count on it.
When a Cash Sale Is the Wrong Choice for a Reverse Mortgage Home
If the inherited house is in good condition, you have months left on the servicer’s clock, and the equity is large, list it with a broker. A cash sale is the right tool for speed and simplicity, not for topping the market.
My offer will be lower than retail. No cash buyer pays full market value, and anyone who says otherwise is not showing you the math. The honest comparison is what you net. That means the sale price minus repairs, selling costs, and the months of interest and carrying costs while you wait. My post on cash offer versus listing breaks that comparison down line by line.
A cash sale also fits poorly on an underwater house where my number would land below the 95% floor. In that case, I will tell you so, and a listing or a deed in lieu is likely the cleaner route.
Where a cash sale does fit: the house needs work the estate cannot fund, the heirs live out of state, the deadline is close, the house is full of belongings, or siblings want a clean split on a known date. In those cases, a firm price and a closing date you pick are worth more than a higher number you might not reach in time.
How to Check Any Buyer Before You Sign
Ask any buyer for proof of funds, ask whether they will take title in their own name or assign the contract, and confirm the closing runs through a licensed title company. Those three questions sort out most problems before they start.
Assignment is the one most heirs miss. Some buyers sign a contract, hold only an equitable interest, and then sell that contract to someone else. That is wholesaling. Oregon now requires residential property wholesalers to register with the state and give written disclosures. The Oregon Real Estate Agency’s wholesaler page explains the registration. If you have a specific question about a contract, ask an Oregon real estate attorney.
Here is how I work, so you can hold me to it. I take title in my own name, and I do not assign contracts. I provide proof of funds on request, as a bank letter or statement. Every closing runs through a licensed and insured title company, and you can call the title company directly for updates. My offer does not change at closing. There are no last-minute deductions; I pay all closing costs, and you pay no commissions or fees. I also shred any sensitive papers I find after closing, like tax returns and bank statements.
Christina C. sold her late mother’s home with her brothers. She wrote: “He came the day we called and did a walk thru. Gave us an offer the following day.” Portland Cash Buyers is BBB A+ accredited and Google 5-star rated, and you can read more reviews from Portland-area families. You can also learn more about how I work and who I am.
I see every house with a private walk-through. If you live out of state and cannot meet me, I can make a sight-unseen offer from your description and photos. I buy across the metro, from houses in Portland to the surrounding counties.
Frequently Asked Questions About Inheriting a House With a Reverse Mortgage
These cover the questions heirs ask most. More general answers are on my FAQ page.
Can the bank take the house right after the borrower dies?
No. Under HUD rules for HECMs, heirs typically get about 30 days to state a plan after the due and payable notice and up to six months to sell or pay off. Extensions may follow with approval. Foreclosure comes only after those windows close.
What if the house is worth less than the reverse mortgage?
Heirs owe nothing beyond the house. A HECM is non-recourse. Selling for at least 95% of the appraised value satisfies the loan, and FHA insurance covers the rest. A deed in lieu of foreclosure is another way out. Neither leaves the heirs with a personal debt.
Can I live in my parent’s house if it has a reverse mortgage?
Yes, if you pay off the loan. Heirs who keep the house pay the lesser of the full balance or 95% of the appraised value. Most do this with a new mortgage in their own name. You cannot take over the reverse mortgage itself.
Does a reverse mortgage go through probate?
The loan does not, but the house often does. If the house was in the borrower’s name alone, a personal representative usually needs court authority to sell it. The reverse mortgage deadline keeps running during probate, so open the estate early and keep the servicer informed.
Can Portland Cash Buyers buy a house that still has a reverse mortgage?
Yes. Quinn Irvine buys inherited houses with reverse mortgages as-is. The title company pays off the servicer from the sale proceeds at closing, and the estate receives the rest. A typical close takes 7 to 14 days, and the estate chooses the date. On an underwater house, the price must still meet the servicer’s 95% floor.
Your Next Step With an Inherited House With a Reverse Mortgage
Start by reviewing the servicer’s notice and confirming your exact deadlines in writing. Keep the property insured, make sure property taxes are addressed, and contact a HUD-approved housing counselor if you need help comparing a sale, payoff, or deed in lieu of foreclosure. If probate is required, ask an Oregon probate attorney about the authority needed to sell the home before the loan deadline.
If selling makes sense, request a cash offer and compare the expected net proceeds with a traditional listing before committing. I can provide a no-obligation offer within 24 hours. Closing speed depends on title work, estate authority, and the servicer’s requirements. Call or text me at (503) 770-0145 to discuss your property.
This article is general information, not legal or tax advice. For deadlines and authority specific to your estate, contact your servicer, a HUD-approved housing counselor, or an Oregon attorney.