If you are deciding whether to sell your house before or after retirement, a quick house cash sale for ret irement is one option to compare with a traditional listing. Selling before retirement usually makes sense if you need the equity to fund retirement, still carry a mortgage, or want to buy your next home while you can still qualify with work income. Waiting can make sense if the home is paid off, affordable to keep, and you are still deciding where you want to live.
I’m Quinn Irvine, owner of Portland Cash Buyers, and I have bought homes in the Portland area since 2004. This guide compares the financial and practical trade-offs of each option, including mortgage qualification, taxes, Medicare premiums, and your next living arrangement.
Here are a few things most retirement timing guides skip:
- Your paycheck is a mortgage tool. Lenders can count retirement income, but a loan file built on steady work income is often simpler to approve.
- Medicare looks back two years. Social Security sets the extra Medicare premium charge using your tax return from two years earlier, so a big taxable gain at 63 or later can follow you.
- Oregon helps some people stay. Eligible homeowners 62 and older can have the state pay their property taxes now and repay them later, usually when the home sells.
- The closing date can be yours to pick. In a cash sale, you can set the date around your retirement and even stay in the home for a while after closing.
Is It Better to Sell Your House Before or After Retirement?
It is better to sell before retirement when your money, your mortgage, or your next purchase depends on the sale. It is better to wait when the house is paid off, cheap to keep, and you still want time to decide. Many homeowners fall somewhere in between. The table below lays out the trade-offs side by side.
| Factor | Sell before you retire | Sell after you retire |
| Qualifying for the next mortgage | Usually simpler with pay stubs and W-2s | Still possible with documented retirement income |
| Access to your equity | Cash is ready on day one of retirement | Equity stays in the house until you sell |
| Medicare premiums | A gain taken before 63 is generally outside the lookback for your first Medicare year | A large taxable gain at 63 or later can raise premiums two years later |
| Time and energy | You juggle work, packing, and a move at once | More time to sort belongings and decide |
| Carrying costs | Taxes, insurance, and upkeep stop sooner | You keep paying them while you decide |
| Where you live next | You need a plan, or a short-term rental | You can try retirement first, then choose |
Neither column wins for everyone. The right answer comes from three questions. Do you need the cash? Do you still owe on the house? Do you know where you want to live? If you answer yes to the first two, selling sooner usually lines up better. If you answer no to all three, waiting is often fine.
5 Signs It’s Time to Sell Your Home Before You Retire
It is time to sell before you retire when the house costs more than it gives back, or when your retirement plan only works with the equity in hand. Here are five signs that point toward selling first.
- Your retirement budget needs the equity. If savings alone can’t cover the years ahead, the house may be your largest asset. Selling while you still earn lets you plan with real numbers instead of guesses.
- You still carry a mortgage payment. A payment that feels fine on a salary can feel heavy on Social Security and a pension. Paying it off at closing removes the biggest monthly bill many people have.
- You plan to buy again with a loan. If your next home needs financing, applying while you are still working is often simpler. I cover that in more detail below.
- The house no longer fits your body or your days. Steep stairs, a big yard, and a long repair list don’t get easier with age. If you already put projects off, the list will be longer in five years.
- You are leaving the Portland area. Many people retire closer to their kids or somewhere sunnier. If that’s you, my notes on moving out of state and my page on relocating from the Portland area explain how to sell from a distance.
If one or more of these fits, I’m glad to show you a cash offer next to a listing estimate, with the math written out. Call or text me at (503) 770-0145, seven days a week, 8 am to 8 pm. There is no obligation. If the numbers point toward listing, I’ll say so.
When It Makes Sense to Wait Until After You Retire
Waiting makes sense when the house is paid off, the yearly cost fits your retirement income, and you are not yet sure where you want to land. Retirement changes how people spend their days. Some find they love the garden they never had time for. Others find the house feels too big within a year. Waiting gives you room to find out. It also lets you sort decades of belongings at your own pace, instead of on a moving company’s schedule. If a pension start date or a final paycheck is coming, waiting a few months can keep your income steady during the move.
The trade-off is that the house keeps costing money while you decide. Property taxes, insurance, utilities, and repairs don’t pause. An older roof or a tired furnace can turn into a large bill at a bad time. Waiting is a sound plan when you choose it on purpose. It gets harder when it happens because the decision kept getting pushed back. One more timing note applies if you move out first and rent somewhere else. The home sale tax rules have a clock, and I cover it in the tax section below.
Do You Need to Sell Before Buying Your Retirement Home?
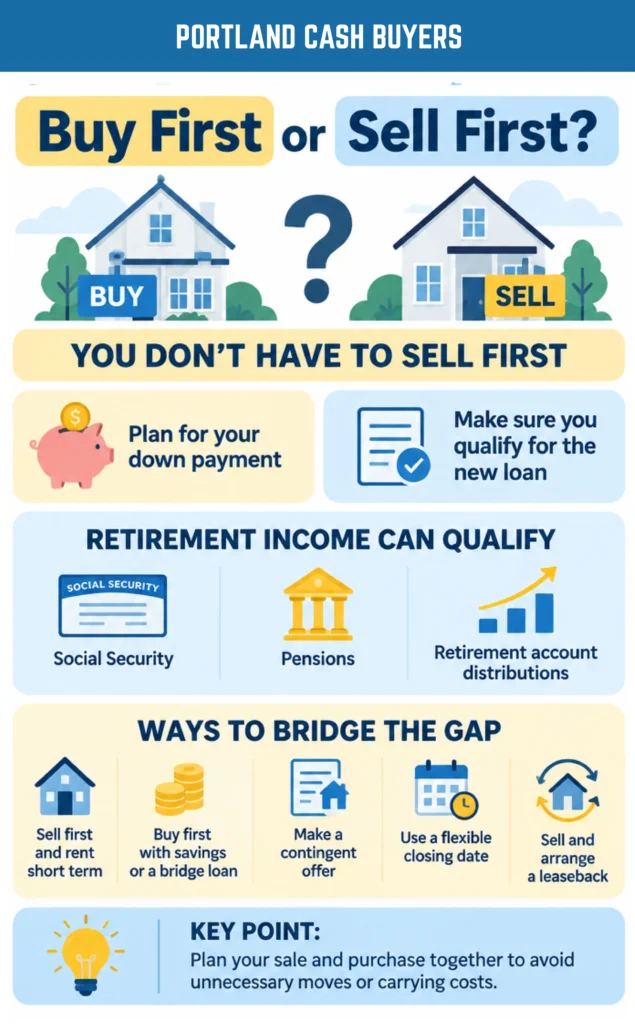
No, you do not have to sell first. You do need a plan for two things: the down payment and qualifying for the new loan. If you can pay cash for the next home, the order matters much less.
Qualifying for a Mortgage With Retirement Income
Yes, you can get a mortgage after you retire. Lenders can count documented income such as Social Security, pensions, and regular retirement account distributions. Federal law also protects you here. The Consumer Financial Protection Bureau explains that under the Equal Credit Opportunity Act, a creditor generally cannot use your age to make credit decisions.
Still, the paperwork changes. A lender may want award letters, account statements, and proof the income will continue. Some people find it simpler to lock in the new loan before they leave work, while pay stubs and W-2s tell a clean story. Talk with a lender early, ideally well before your retirement date, so you know which path is easier for you.
Bridging the Gap Between Selling and Buying
The hard part is the gap between the two closings. Most retirees need the equity from the old house to buy the new one, but they don’t want to move twice. Here are the common ways people bridge it.
| Option | How it works | What to watch |
| Sell first, rent short-term | You close, move to a rental, then buy | Two moves and short-term rent costs |
| Buy first with savings or a bridge loan | You buy the new home, then sell the old one | Carrying two homes, plus loan costs and approval |
| Contingent offer on the new home | Your purchase depends on your sale closing | Sellers in a busy market may pass on it |
| Flexible closing date | You set the sale date to match the move | Needs a buyer who can be flexible |
| Leaseback after closing | You sell, get paid, and stay for an agreed period | Get the move-out date and terms in writing |
The last two are where I can help. When I buy a house, the seller picks the closing date, short or long. I also offer a leaseback when someone needs more time after closing. That means you can have cash in hand to buy your next place while you still live in the old one.
Should You Sell and Rent in Retirement?
Selling and renting fits retirees who want their equity freed up and repairs off their plate. Keeping a paid-off home usually costs less each month. The right choice depends on what matters more to you: the lowest monthly bill or the most flexibility.
| Factor | Keep a paid-off home | Sell and rent |
| Monthly housing cost | Taxes, insurance, utilities, and upkeep | Rent, renter’s insurance, and utilities |
| Repairs | Yours to plan for and pay | The landlord’s job |
| Your equity | Stays locked in the house | Freed up to invest, spend, or gift |
| Future cost changes | Taxes and insurance can rise | Rent can rise at each renewal |
| Flexibility | Moving means selling first | Easier to move closer to family later |
To compare fairly, add up the full yearly cost of owning. Include property taxes, insurance, routine upkeep, and a reserve for big repairs. Then compare that number to local rents for the kind of place you want. A paid-off house often wins on monthly cost. Renting often wins on flexibility and freed-up cash. Some people try a middle path and keep the house as a rental. That can work, but it makes you a landlord in retirement. Before you choose that route, read my comparison of whether to sell or rent out your house.
Downsize Now or Later? How Timing Affects Taxes and Medicare
Downsizing earlier usually keeps more tax and Medicare options open. Downsizing later works fine when your gain is modest or well under the home sale exclusion. If you are leaning toward a smaller place, my page on downsizing your Portland home covers the practical side. This section covers the money side. It is general information, not tax advice, so please run your own numbers with a tax professional.
The Home Sale Exclusion When You Sell Before or After Retirement
The federal home sale exclusion works the same before or after retirement. According to IRS Topic 701, Sale of Your Home, you may be able to exclude up to $250,000 of gain from your income, or up to $500,000 if you file a joint return with your spouse. To qualify, you generally must have owned and lived in the home as your main home for at least two of the five years before the sale. You generally can’t use the exclusion if you used it on another home in the two years before this sale.
Two retirement situations deserve a closer look. First, long-time Portland owners can have gains larger than the exclusion, especially if they bought decades ago. Second, if you move out and rent first, the two-of-five-year clock keeps running. Wait too long to sell, and you may lose the exclusion. A tax professional can tell you where you stand and how your Oregon return is affected.
Why a Sale at 63 or Later Can Affect Medicare Premiums
Medicare premiums can increase when your modified adjusted gross income exceeds the applicable threshold. Social Security generally uses federal tax-return information from two years earlier to determine the income-related monthly adjustment amount, or IRMAA. A taxable gain from selling your home may affect those premiums if the gain increases your reported income after any applicable home-sale exclusion. For someone enrolling in Medicare at 65, a taxable gain reported for the year they turn 63 may affect their initial premiums. The exact impact depends on the tax year, the taxable gain, and the income thresholds that apply.
| Age when you sell | Premium year that uses that tax return | What it means |
| 62 | Age 64 | Usually before Medicare starts at 65 |
| 63 | Age 65 | Can affect your first year of Medicare premiums |
| 65 | Age 67 | Can raise your premiums for that year |
| 70 | Age 72 | Can raise your premiums for that year |
This only matters if the gain is taxable. If the whole gain falls under the exclusion, it generally won’t raise your income for this purpose. Social Security does let people ask to lower IRMAA after certain life-changing events, such as marriage, divorce, the death of a spouse, or a loss of income. A one-time gain from selling your house is not one of the events on that list. That is why planning the timing of a large taxable sale matters more than trying to fix it afterward.
Staying Put in Portland: Costs and Oregon Programs to Know
Staying put works well when you budget for the full yearly cost of the house. Oregon’s property tax deferral can ease part of that cost for eligible owners. If you live in Multnomah, Washington, or Clackamas County and plan to stay, here is what to budget for.
| Cost of staying | What to check |
| Property taxes | Your latest county tax statement and any deferral eligibility |
| Homeowners insurance | Renewal premiums and what the policy covers |
| Routine upkeep | Gutters, yard work, moss, and seasonal maintenance |
| Big repairs | Age of the roof, furnace, water heater, and sewer line |
| Accessibility changes | Stair rails, a main-floor bedroom, or a walk-in shower |
Oregon’s Senior and Disabled Property Tax Deferral Program lets eligible homeowners borrow from the state to pay their county property taxes. The state records a lien on the property, and the deferred taxes accrue simple interest at 6% per year. For 2026, the household income limit is $70,000, based on income from 2025. The program also has a $500,000 net-worth limit that excludes the home and personal property, as well as property-value limits that depend on the county and applicable eligibility rules. Applicants generally must be at least 62 years old for the senior program and meet residency requirements. Check the Oregon Department of Revenue’s current deferral rules before deciding whether staying in the home is affordable.
The deferred taxes and interest get repaid later, usually when the home sells, or the owner moves. If you sell a house with a deferral lien, the title company pays it off from the sale proceeds, the same way it handles a mortgage payoff. When I buy a house, any liens are paid off at closing, and I walk you through the math so you know your net.
How to Sell on Your Retirement Timeline
You sell on your retirement timeline by picking the closing date first, then choosing the sale method that can hit it. A traditional listing and a cash sale run on very different clocks.
| Step | Traditional listing | Cash sale to me |
| Getting ready | Repairs, cleaning, and staging are common | None needed, because I buy as-is |
| Time to an accepted offer | Portland metro total market time reached 68 days in September 2026, based on the latest published September RMLS market report. | A cash offer within 24 hours of your request |
| Property access | Repeated public showings and open houses | A private walk-through with me, or a sight-unseen offer from your photos |
| Contingencies | Financing, appraisal, and inspection contingencies are common | No financing contingency |
| Closing | After the buyer’s loan, appraisal, and inspection clear | Typically 7 to 14 days, or a later date you choose |
| After closing | You usually move out at closing | Leaseback available if you need more time |
The RMLS figure counts days from listing to an accepted offer. It does not include the weeks a financed buyer still needs to close. That is why a retirement date and a listing date can be hard to line up.
Selling to me runs in three steps. You tell me about the home by form or phone. I review the comparable sales and walk through the property privately, or make an offer from your photos. Then you pick a closing date at a licensed and insured title company. I pay all closing costs. There are no commissions and no fees to you. I take title in my own name, and proof of funds is available on request.
My offer math is not a secret. I show you the comparable sales I used, the condition, the repair costs, and the carrying costs. Then we walk through it together. The offer doesn’t change at closing with last-minute deductions.
Selling as-is matters more in retirement than people expect. A house lived in for 30 years often needs a roof, electrical updates, or simply a lot of sorting. You can leave belongings behind. If your house needs work you don’t want to take on, the repairs may not pay for themselves.
For a fuller side-by-side, see my breakdown of a cash offer vs. listing with an agent. Flexible timing works in practice, too. Christina C. sold her late mother’s home with her brothers. She shared that I came out the day they called, did a walk-through, and made an offer the next day. I also gave them extra time, and the closing went smoothly and quickly.
When a Cash Sale Is the Wrong Move for a Retiree
If your house is in good condition, you have a few months, and the market is strong, list it. A cash sale is the right tool for speed and simplicity, not for topping the market.
My cash offer will be lower than retail. The honest comparison is what you net. After agent commissions, repairs, seller closing costs, and months of carrying costs, the gap is often smaller than the sticker price suggests. Sometimes it is still large, and then listing is the better choice for you.
A cash sale tends to fit retirees when:
- The house needs repairs you don’t want to fund or manage.
- Your retirement date or move date is fixed, and a listing can’t promise to hit it.
- You want a private walk-through instead of repeated public showings.
- You need time after closing to move, and a leaseback solves that.
If none of those fit, I will tell you so. Lindsay L. was nervous about selling without a lawyer or a realtor. She said everything I told her played out exactly as promised, with no bad surprises. You can read more seller stories or about us before you call. We are BBB A+ accredited and Google 5-star rated.
Frequently Asked Questions About Selling Your House Before or After Retirement
Can I get a mortgage after I retire?
Yes. Lenders can qualify you using documented retirement income such as Social Security, pensions, and retirement account distributions. Under the Equal Credit Opportunity Act, a lender generally cannot use your age to make credit decisions. Some buyers still find it simpler to secure the new loan before leaving work, while pay stubs and W-2s are easy to document. Talk with a lender early.
Can I sell my house and stay until my next place is ready?
Often, yes. Flexible closing dates and short stays after closing are common with direct buyers, and sometimes possible in a traditional sale. We let the seller choose the closing date and offer a leaseback when a seller needs more time after closing. Whatever route you take, get the move-out date and terms in writing in the purchase agreement.
Does Oregon offer property tax help for seniors who want to stay?
Yes. Oregon’s Senior and Disabled Property Tax Deferral program lets eligible homeowners age 62 and older postpone property taxes. The state pays the county and records a lien, and the taxes are repaid with interest, usually when the home sells. Income, net worth, and residency limits apply. Check the current rules with the Oregon Department of Revenue or your county assessor.
Is it cheaper to rent or own in retirement?
It depends on whether your home is paid off. A paid-off home usually costs less each month than rent. Selling and renting, though, frees up equity and removes repair bills. Compare your full yearly cost of owning, including taxes, insurance, and upkeep, against local rents for the kind of place you want.
Should I downsize before or after retirement?
Downsizing before retirement often makes the next mortgage easier and keeps a large taxable gain out of the Medicare lookback years. Downsizing after retirement gives you time to decide where you want to live. If your gain is well under the home sale exclusion, the tax side matters less. A tax professional can confirm how your own numbers work.
Do I have to fix up my house before selling it in retirement?
No. Repairs can raise the price in a traditional listing, but they cost money and time up front. We buy Portland-area homes as-is, including homes with dated systems, deferred repairs, or a lifetime of belongings inside. If your home is already in good shape, listing it may net you more.
For other questions, the full FAQ page covers how my offers and closings work.
Deciding When to Sell Your House Before or After Retirement
Whether you sell your house before or after retirement comes down to three things: cash, mortgage, and where you want to live. If the equity funds your plan or the payment strains your budget, selling sooner usually lines up better. If the house is paid off and easy to keep, waiting is a reasonable choice. Either way, check the tax and Medicare timing with a professional before you set a date.
Whether you sell before or after retirement, compare the estimated proceeds with the cost of keeping the house, including property taxes, insurance, upkeep, and any mortgage payments. If you have a large taxable gain, check the potential tax and Medicare effects with a qualified professional before setting your closing date.
If a direct sale fits your timeline, get a no-obligation cash offer from us. I provide an offer within 24 hours, explain the comparable sales and cost estimates, and work with you on the proposed closing date. If you need to remain in the home after closing, confirm whether a written occupancy agreement is available before relying on it. Call or text (503) 770-0145 to compare your options.
This article is general information, not financial, tax, or legal advice. Please confirm your own situation with a tax professional or financial advisor.