Selling a house during a military PCS comes with strict deadlines, limited flexibility, and important financial decisions that can affect your move. If you’re relocating from Portland and need to sell, understanding your options early can help you avoid unnecessary delays and extra costs. I’m Quinn Irvine, owner of Portland Cash Buyers, and since 2004, I’ve helped more than 1,000 Portland-area homeowners, including military families stationed near Camp Withycombe and those commuting from Joint Base Lewis-McChord, sell on timelines that fit their orders rather than the housing market.
Selling your house during a military PCS usually comes down to three paths: list with an agent and hope it closes before your report date, rent it out and manage it from your next duty station, or sell directly for cash and set your own closing date. The fastest of the three, a direct cash sale, can close in as few as 7 days once you accept an offer, which is often the only option that reliably beats a fixed PCS clock.
Key Takeaways
- A direct cash sale can close in 7 to 14 days, or as fast as 3 if your report date requires it, versus 3 to 6 months for a typical financed listing.
- Service members can suspend the 5-year ownership-and-use test for the IRS home-sale exclusion for up to 10 years while on qualified official extended duty.
- Selling and paying off a VA loan in full restores your entitlement, though the restoration itself isn’t automatic; you or your lender need to request it from the VA
- Renting out your Portland home during a PCS means becoming a long-distance landlord and can affect how much of the home-sale exclusion you keep later.
- At Portland Cash Buyers, I work directly with military families on tight report-date timelines, no call center, no rep, no wholesaler markup.
Selling Your House on a Military PCS Timeline
Selling your house on a military PCS timeline starts with your report date, then works backward. If you’ve got 60 to 90 days before you need to be at your next duty station, a traditional listing can sometimes work, provided the house is in market-ready condition, and you can manage showings around packing and household goods pickup. If you’re inside 30 days, or your household goods crew is already scheduling pickup, a direct cash sale is usually the only path that reliably closes before you have to leave. I lay out the full timeline in my guide to selling a house during an out-of-state relocation, including the week-by-week milestones that apply to any move, military or civilian.
Here’s the honest math. A financed buyer’s loan can take 30 to 45 days to close even after you accept an offer, and that’s before repairs, inspection negotiations, or an appraisal that comes in low. None of that fits neatly around a report date that the Army, Navy, Air Force, Marine Corps, Coast Guard, or Space Force sets for you, not the market.
For general PCS planning beyond the house itself, my page on relocating from Portland when you need to sell covers the broader relocation situation I help with across the metro, and my main page on selling your house walks through how a direct sale works for any Portland homeowner, PCS orders or not.
The Military Capital Gains Exclusion Extension
The military capital gains exclusion extension lets you pause the standard 5-year ownership-and-use test for up to 10 years while you’re on qualified official extended duty. Normally, to exclude gain on the sale of a main home, you must have owned and lived in it for at least 2 of the last 5 years. Frequent PCS moves can make that test hard to meet, so Congress built in relief.
Qualified Official Extended Duty, Explained
You’re considered on qualified official extended duty when you’re called to active duty for more than 90 days, or for an indefinite period, at a duty station at least 50 miles from your main home, or while living in government quarters under orders. If that describes your situation, you can elect to suspend the 5-year test period for up to 10 years total, and you can only suspend it for one property at a time.
Say you bought a home near Vancouver, lived in it for two and a half years, then received PCS orders and moved away for six years of qualifying duty. You can disregard those six years and count backward from before your duty began, which can still let you meet the ownership and use tests when you finally sell.
This suspension applies to the ownership and use test, not to whether you owe tax at all, and it doesn’t remove the underlying $250,000 single-filer or $500,000 married filing jointly exclusion cap. It simply gives you more years to work with when your PCS orders don’t line up with a clean 5-year window.
Every service member’s timeline is different, so this is general information, not tax advice. Confirm your specific situation against IRS Publication 3, Armed Forces’ Tax Guide or with a tax professional before you file.
VA Loan Considerations When You Sell
VA loan considerations when you sell come down to how your loan gets paid off and what happens to your entitlement afterward. There’s no prepayment penalty on a VA loan, so you can sell whenever your PCS orders require it without an early-payoff fee.
- Selling and fully paying off the loan is the simplest path. Once the balance clears at closing, you can request that the VA restore your entitlement for your next purchase.
- Restoration isn’t automatic. Paying off the loan removes the VA’s lien on the property, but you or your lender still need to request restoration through the VA before it shows up on your Certificate of Eligibility.
- A loan assumption is possible if a qualified buyer takes over your existing VA loan and rate, though your entitlement then stays tied to that property until the assuming buyer’s own entitlement substitutes for yours.
- A one-time restoration is available even if you keep the property, as long as the VA loan on it has already been paid off. This option only applies once, so PCS families juggling a prior rental sometimes save it for a future move rather than using it early.
Restoring Your VA Entitlement After the Sale
Once your sale closes and the loan is paid off, confirm with your lender or the VA that restoration has actually processed. Don’t assume it’s done just because the house sold. If you want to use a VA loan again at your next duty station, having your entitlement confirmed on file avoids a scramble later. If your loan balance is higher than your sale price, talk with your lender about your options well before closing, since a shortfall changes what has to happen at the table.
Loan Assumption: An Option Worth Understanding
If your VA loan carries a lower rate than what’s available today, a buyer, veteran or civilian, may be able to assume it. That can make your house more attractive on a tight timeline, but a direct sale to me sidesteps the assumption approval process entirely since I close with my own funds, not financing that has to be underwritten. Details on VA loan mechanics are available directly from the VA home loan information page.
Sell, Rent, or Use Property Management During a PCS?
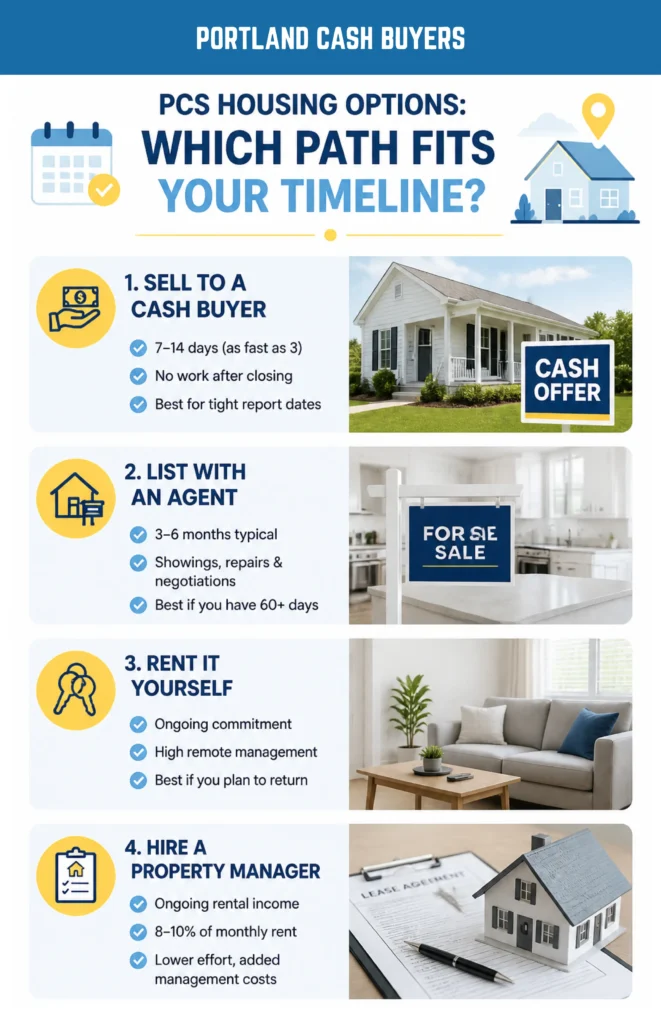
Sell, rent, or use property management during a PCS is a real decision, not just a sale-versus-no-sale question, and each path has a different cost and time commitment attached.
If you’re weighing whether your BAH at your new duty station will cover a property manager and the mortgage on the Portland house at the same time, run the numbers before you decide, not after you’ve signed a lease with a tenant. A property manager typically charges 8 to 10 percent of monthly rent, and that’s before maintenance, vacancy between tenants, or a repair that comes up while you’re stationed somewhere else entirely.
| Option | Time to Execute | Ongoing Effort | Best Fit |
| Sell to Portland Cash Buyers (direct cash sale) | 7 to 14 days, as fast as 3 | None after closing | Report date is close or fixed |
| List with an agent | 3 to 6 months typical | Showings, repairs, negotiation | 60+ days before report date, market-ready home |
| Rent it out yourself | Ongoing | High, managed remotely | Strong local rental demand, plan to return |
| Hire a property manager | Ongoing | Moderate, but costs 8 to 10% of rent typically | Want rental income without daily management |
If renting appeals to you, I cover the full trade-off, including the hidden costs of long-distance landlording, in my guide on whether to sell or rent your house when relocating. And if a rental you already own is turning into a headache from a prior duty station, my page on what to do when a rental property becomes a problem covers that situation directly. I’ve worked with Portland-area families choosing between all four of these paths, and the right answer usually comes down to how much runway you have before your report date.
Selling Fast Before Your Report Date
Selling fast on a tight military timeline means front-loading every decision that can be made now. Get your paperwork together, the deed, loan payoff statement, and any HOA or property tax records, as early as possible so nothing holds up closing later.
Household goods pickup dates and moving-truck reservations tend to lock in well before a listing would close, which is exactly why so many PCS sellers end up choosing a direct sale over a traditional one. You’re not just selling a house; you’re coordinating it against a government-scheduled move you don’t control.
- Request a loan payoff quote from your lender the same week you get orders.
- Decide to sell, rent, or assume based on your actual report date, not a hopeful one.
- If selling, get a no-obligation cash offer request in early so you have a number to plan around.
- Coordinate your closing date with your household goods pickup so you’re not paying to store furniture in an empty house.
- Close through a licensed, insured title company regardless of who buys, so the paperwork and payoff are handled cleanly.
If a financial squeeze is part of what’s driving the timeline, whether that’s carrying two households or a hardship separate from the move itself, my page on financial emergencies covers options beyond the PCS itself. Whenever you’re ready to talk specifics, my contact page reaches me directly, not a call center.
How a Cash Sale Simplifies a Military PCS House Sale
A cash sale simplifies a military PCS house sale by removing the two things most likely to blow past your report date: financing risk and repair negotiations. I buy homes as-is, so a house that needs work before it could pass a lender’s appraisal doesn’t need to be fixed first.
I review the property, in person or sight-unseen if your timeline requires it, and present a no-obligation cash offer within 24 hours. You pick the closing date, I pay all closing costs, and there’s no commission because there’s no agent. The number I quote is the number you get at closing, with no last-minute deductions.
The offer itself is built from neighborhood comps, the home’s condition, likely repair cost, and carrying costs, not a black-box formula. If your orders change or your timeline shifts, that no-obligation part is real: you’re free to walk away from the offer if it stops making sense for your move.
PCS families tell me some version of the same thing: the timeline was tight and complicated, and the closing date held anyway. You can read more experiences like that from families in similar situations on my testimonials page. I’m not a wholesaler putting your house under contract to resell it for a fee. I buy directly with my own funds and can show proof of funds on request, which matters more than ever now that Oregon’s HB 4058 requires wholesalers to register and disclose their role to sellers. You can read more about how I work on my about us page.
Want to see what a fast, no-obligation offer looks like before your orders lock you into a date? I can usually turn one around within 24 hours.
PCS Home-Sale FAQs
How fast can I sell my house with PCS orders?
A direct cash sale can close in as little as 3 days if your report date requires it, though 7 to 14 days is typical. A traditional financed listing usually takes 3 to 6 months from listing to close.
Do military members get extra time for the capital gains exclusion?
Yes. You can suspend the standard 5-year ownership-and-use test for up to 10 years while on qualified official extended duty at least 50 miles from your home or in government quarters under orders. This is general information, not tax advice, so confirm your specific case with a tax professional.
Can I sell a house with a VA loan?
Yes, and there’s no prepayment penalty. Sale proceeds pay off the loan balance at closing, after which you can request that the VA restore your entitlement for future use. Portland Cash Buyers can walk you through the payoff process at closing if you’re not sure where to start.
Should I rent out my house during a PCS instead of selling?
It depends on your equity, your appetite for long-distance landlording, and whether you expect to return to Portland. Renting works for some families, but it means becoming a long-distance landlord managed from your next duty station, so weigh that effort honestly before committing.
What if my orders come before the house sells?
You’ll likely need to carry two housing costs, arrange remote closing through a title company, or move to a faster sale option like a direct cash offer to close the gap before you have to report.
Can I close remotely if I’ve already moved?
Yes. Most title companies regularly help military homeowners complete remote closings. Depending on the circumstances, documents may be signed using overnight mail, a mobile notary, or approved electronic signing methods, allowing you to complete the transaction without returning to Oregon.
Military PCS Selling House Guide for Your PCS Timeline
If your PCS orders have already arrived, time is one thing you can’t afford to lose. Instead of waiting months for a traditional sale, you can explore a faster option that works around your report date. Getting a cash offer early gives you a clearer plan and the flexibility to decide what makes the most sense for your move.
If you’re selling your home as-is for cash, Portland Cash Buyers can provide a fair, no-obligation cash offer within 24 hours. You won’t need to make repairs, prepare for showings, or pay agent commissions, and you can choose a closing date that fits your PCS timeline, including as little as seven days when needed.
Whether you’re still comparing your options or you’re ready to move forward, learn more about selling your home as-is for cash and see how a direct cash sale can help you relocate with less stress and greater certainty before your next duty station.